Budgets & Time
Part of Project budgets and time tracking
Monitoring project cost before a budget overrun
Spot likely project cost overruns by combining actual cost, distinct commitments and a fresh cost-to-finish estimate before the budget is spent.
To spot a likely cost overrun early, compare the forecast final cost with the approved cost budget at each review. Spending to date may be low while remaining work and committed purchases already exceed what is available. Identify the gap, its cause and the decision needed before the next commitment.
Define the cost boundary
State which approved budget version the review uses, its currency and the costs it covers. Count labour, relevant supplier charges and other agreed expenses on the same basis as the budget. Keep client billing amounts separate from internal delivery cost. A fixed fee, an hourly billing allowance and a delivery-cost ceiling answer different questions even if software calls each a budget.
Use one cut-off for these inputs:
- Actual cost:cost incurred and recorded by the cut-off, including recorded accruals where applicable.
- Outstanding commitments:authorised future spending not already counted in actual cost.
- Other estimated cost to finish:remaining labour and expected costs, excluding commitments counted separately.
- Approved cost budget:the authorised comparison point, with any revision identified.
Add the first three to produce a working forecast final cost. If a supplier cost is already accrued in actuals, exclude it from commitments. If a planned purchase is already in the remaining-cost estimate, do not add it again.
Read the forecast before the spend bar
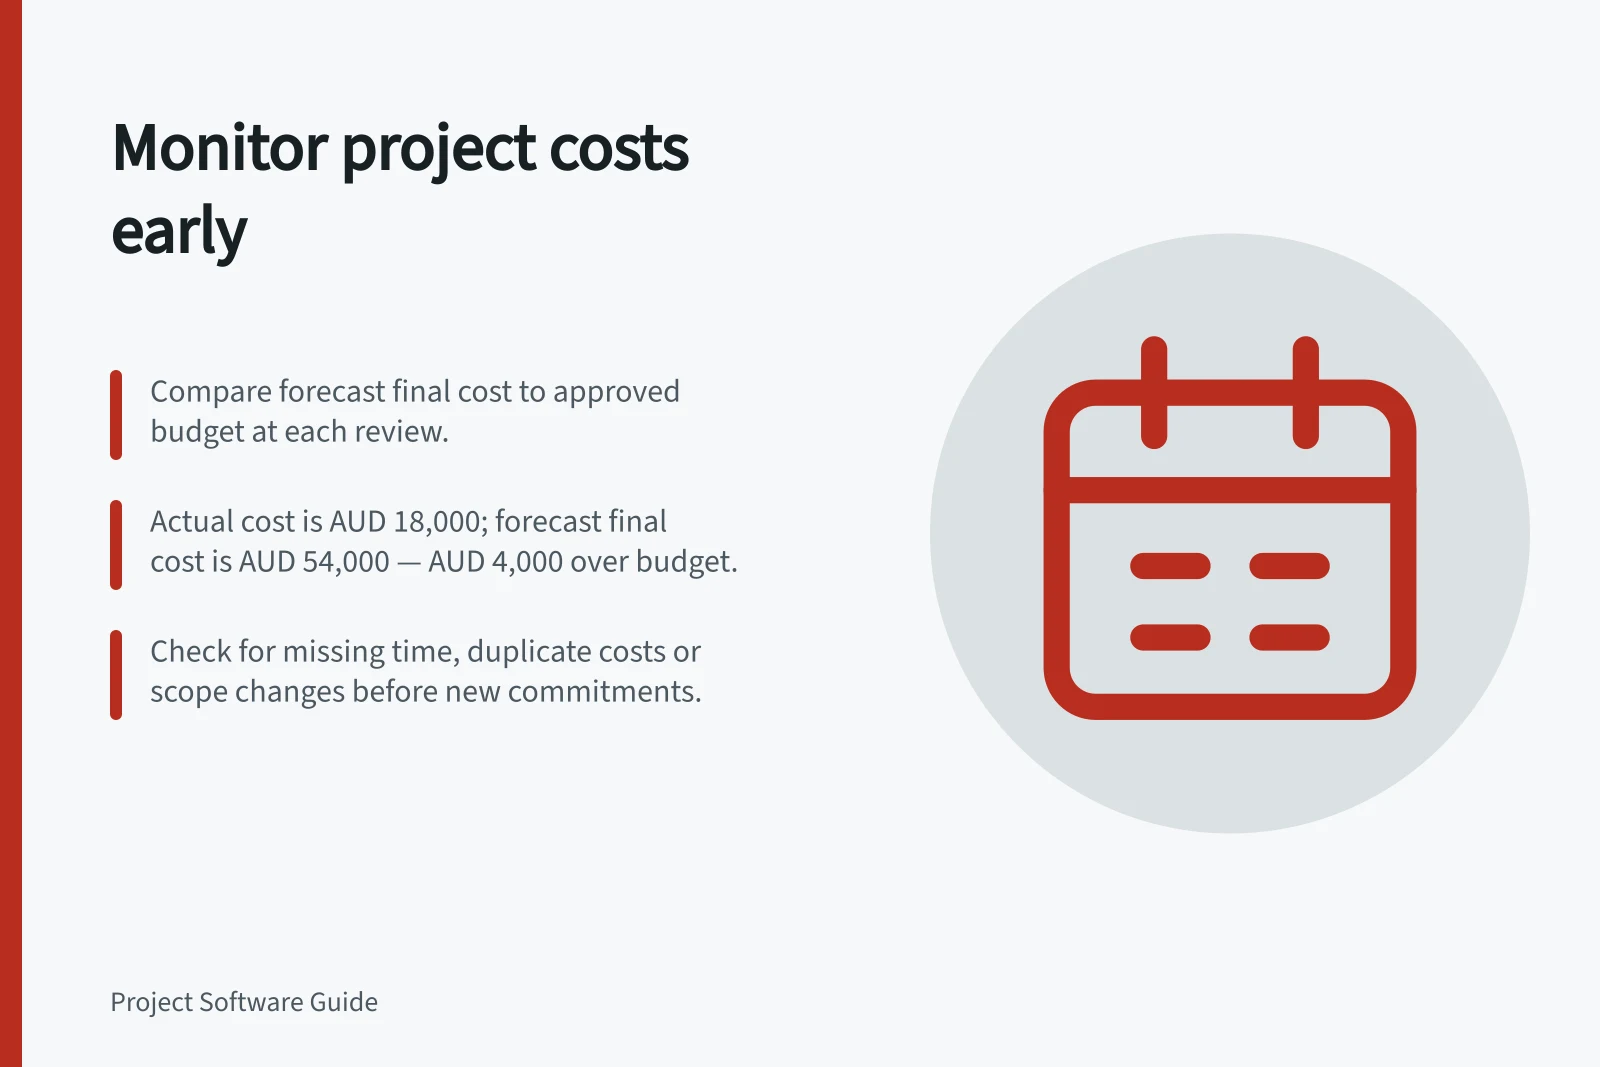
Consider a hypothetical project with an approved AUD 50,000 cost budget. Actual cost is AUD 18,000, distinct outstanding commitments are AUD 12,000, and the team's estimate of other remaining cost is AUD 24,000.
The forecast final cost is AUD 54,000: AUD 4,000 above budget. Actual cost is 36% of the budget, so an alert based only on recorded cost would not reveal this forecast gap.
Ask work owners what changed in the remaining estimate. Does a specialist need more time? Is a deliverable being redone? Has an external quote changed?
Note uncertainty and when a better estimate should be available. A working forecast is not a promise of a precise final cost.
A compact review record shows the budget, actual cost, distinct commitments, other estimated remaining cost, forecast final cost, gap, cause, decision owner and next review date. Identify the work package behind a material movement.
Decide before more cost is committed
If the forecast exceeds the approved budget, check for missing time, expenses and duplicate amounts. Then separate work required by the agreed scope from a proposed change. Options may include reducing avoidable rework, changing the delivery method, deferring a purchase, revising scope with approval or seeking a new budget decision.
State the delivery effect of each option. Preserve the original baseline when an authorised revision is made.
Review ahead of costly decisions, such as a supplier order or staffing extension. Assign someone to refresh the remaining-cost estimate even when no alert has fired.
Check what an alert measures
Clockify says estimate alerts need configured thresholds, are not retroactive and do not automatically stop further time tracking. Treat an alert as a prompt to inspect the project.
Before relying on a dashboard, ask whether its percentage counts hours, billable value, recorded internal cost or expenses. Teamwork.com says budget expenses count towards fixed-fee financial budget usage but not total-hours budgets.
Check the exact budget type, plan and permissions you intend to use. Keep a separate forecast if the tool does not account for remaining commitments and work.